

The Australian Taxation Office (ATO) tests what borrowed money was used for, not what secures it. Debt recycling turns that test into a method, and a single careless transaction can break it for the life of the loan.
The ATO draws a hard line through every home loan in the country, and it has nothing to do with the bank. Interest is deductible only on the portion of a loan used to produce assessable income. The ATO lists incorrect apportionment of interest as the first of its three most common rental property deduction errors, and warns the split must be maintained for the life of the loan, including through any refinance.
With the cash rate at 4.60% after the Reserve Bank of Australia (RBA) decision on 29 September 2026, that line now decides whether thousands of dollars of annual interest is a sunk cost or a deduction.
Debt recycling is the strategy built on it: converting non-deductible owner-occupier debt into deductible investment debt, without increasing total borrowings. Executed cleanly, it is ordinary tax law. Executed loosely, it fails on paperwork.
The rule the whole strategy rests on
Deductibility follows the use of the borrowed funds, not the asset securing them. ATO guidance is blunt on this: interest on a loan for a new home you do not use to produce income is not deductible even where a rental property secures that loan. The reverse holds too, which is what makes debt recycling possible. Borrow to buy an income-producing asset and the interest is deductible, regardless of which property the lender has taken as security.
Mixed loans are apportioned by formula: total interest multiplied by the investment portion divided by total borrowings. The ATO's own example runs a $400,000 loan with $380,000 applied to a rental property, giving a deduction of $33,250 on $35,000 of interest. That 95/5 ratio then applies for the life of the loan. Critically, within a single mixed loan, repayments cannot be directed at the private portion alone; they are applied in the same ratio. That is why debt recycling relies on separate loan splits, not one blended account. Detailed calculations sit at paragraphs 19 and 20 of Taxation Ruling TR 2000/2, the ATO’s ruling on interest on money drawn down under line of credit and redraw facilities.
 Priscilla Cheung
Where debt recycling goes wrong
Four failures account for most of the damage.
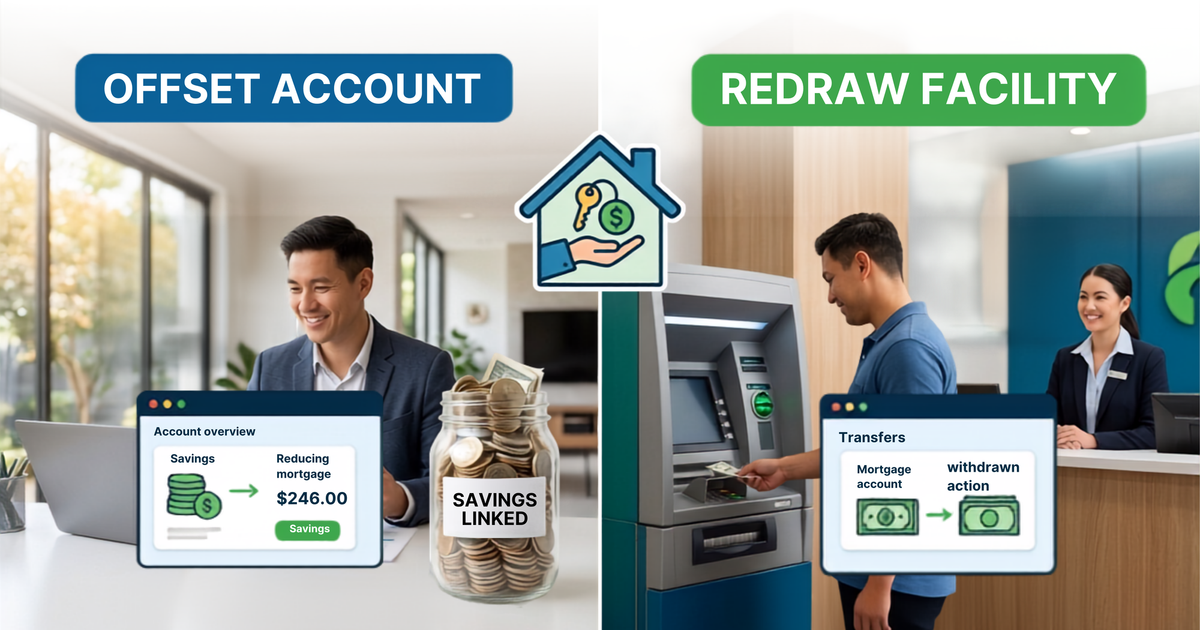
The first is the offset shortcut. Cash sitting in an offset account is your money, not borrowed money. Moving it to a share account changes nothing about deductibility. The character is set at the moment of borrowing, which is why a redraw, not a transfer, is the mechanism that matters.
The second is contamination. One private transaction drawn from an investment split converts a clean loan into a mixed-purpose loan, and the apportionment ratio then follows it permanently.
The third is capitalising interest. In Hart, the High Court in 2004 applied the Part IVA anti-avoidance provisions to a split loan arrangement where interest on the investment portion was capitalised while repayments were funnelled into the home portion. Letting deductible interest compound rather than paying it is the structure that attracts scrutiny.
The fourth is arithmetic. A deduction is not a return. At the 37% marginal rate plus the 2% Medicare levy, a dollar of interest returns 39c. The other 61c is a real cost, carried against a geared investment that can fall.
The six-step method
- Build the surplus. Pay down the owner-occupier loan or accumulate the cash first. Debt recycling redirects existing debt; it does not create the capacity.
- Request a loan split from the lender, not a redraw against the main account. You want a separate loan with its own account number, not a sub-ledger.
- Pay that split down to nil.
- Redraw the full balance of that split in one transaction to a clean account holding nothing else.
- Invest the entire amount in income-producing assets, and keep statements, contract notes and dates.
- Repeat with a new split each time surplus accumulates. Never reuse a split that has been touched by a private transaction.
 Edward Abella
What to settle before the first split
The RBA's Monetary Policy Board next meets on 2 and 3 November 2026, with the decision announced on 3 November. Higher rates cut both ways here: every rate rise lifts the dollar value of the deduction and the dollar cost of carrying the debt, and the deduction never exceeds the expense.
Three things to resolve first. Confirm your lender offers genuine loan splits at no cost, because some price each split as a new facility. Model the strategy at a rate well above today's, since the deductible debt is usually variable and ongoing. And take the structure to an accountant before the first redraw, not after, because the purpose is tested at the moment the funds leave the account and cannot be re-characterised later.
The strategy's appeal is that it does not ask you to borrow more. It asks you to be deliberate about which dollar of debt does what, and to document it.


